

We’re witnessing a huge change in shopping where the most important reader of your product reviews isn’t a person anymore. In our June 2026 study of US adults, two thirds of shoppers said they’re comfortable letting AI summarize reviews instead of reading them. Among people who shop with AI regularly, it’s everyone (96%). Our study also found that 43% of Americans have used AI to shop or research products, that a third of shoppers would abandon AI over a single confident-but-wrong answer, and that 42% would already let an AI agent reorder routine products without asking. These data points show how consumers are changing their behavior and why GEO (Generative Engine Optimization, a fork of SEO) is now so important. An AI model now sits between brands and buyers, doing the reading, the comparing, the recommending, and increasingly the choosing and paying. In this first of two parts, we’ll talk about how that AI recommendation system works and who’s using it. Part two covers where delegation is heading, who’s next, and why understanding it all requires researching the journey at three levels: quantitatively, qualitatively, and mechanically.
AI is the New Shopping Proxy
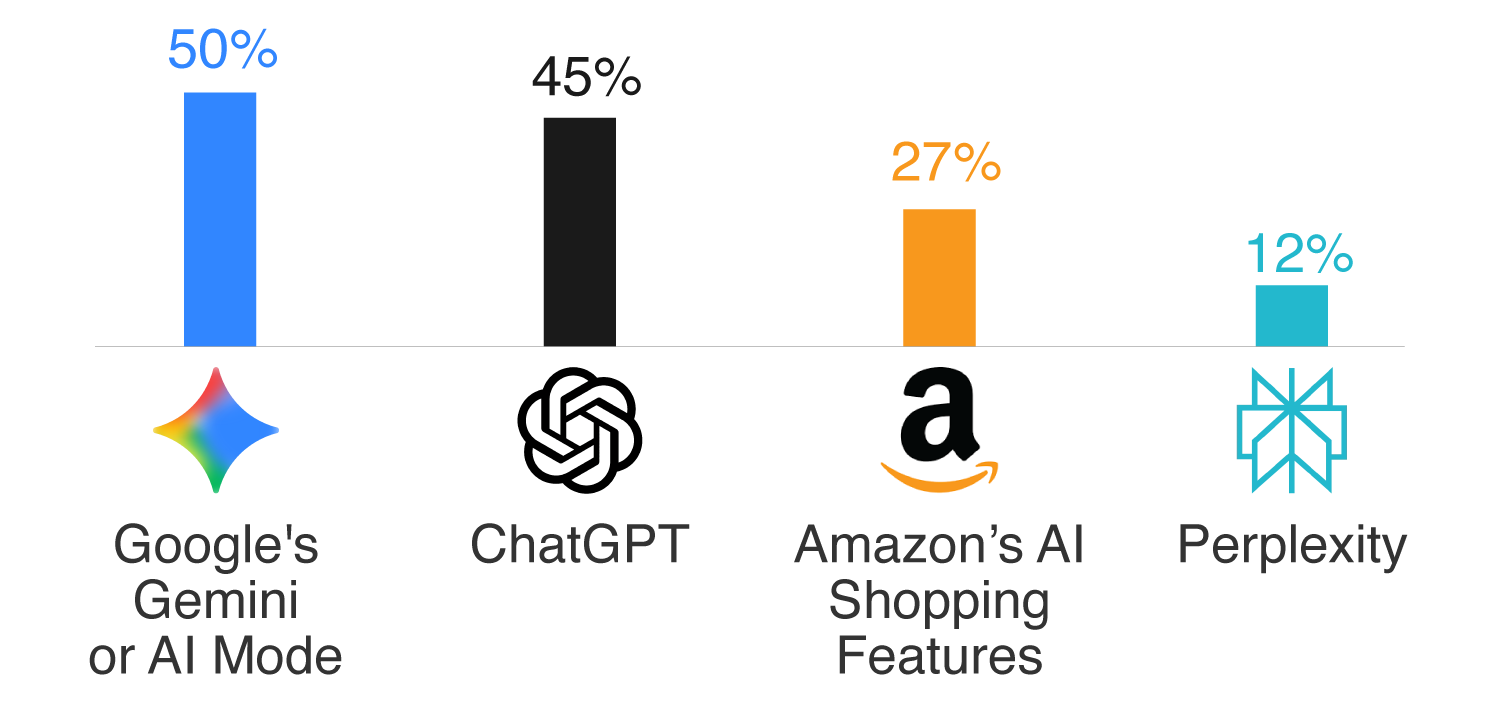
Let’s start with just how big this change of behavior is right now. Forty-three percent of American adults have recently used AI tools to shop or evaluate products and about 1 in 5 do it regularly. Half the country (50%) uses Google’s Gemini or AI Mode at least occasionally, 45% use ChatGPT, a third use Microsoft’s Copilot, and 27% have used Amazon’s AI shopping features. Perplexity, the only standalone AI search company on that list, reaches 12% of consumers. Most don’t decide to start AI shopping. Instead, it will happen to them inside Google and Amazon, which means a brand’s AI representation already impacts the output even for shoppers who say they don’t use AI.
Now let’s look at the early adopters. Any AI shopping use is 54% among Millennials, 54% among parents with kids at home, and 53% in households earning $100K or more, compared to 43% overall. Tighten from any use to regular use and the concentration intensifies: 30% of $100K+ households shop with AI regularly, nearly triple the 11% rate among households under $50K. The buyers with the most disposable income and the highest purchase frequency adopted first, which is a good reason to take this data seriously! The study’s most surprising difference has men at 54% versus women at 34%. However, the story is more nuanced. Our openness data, which we’ll get to in part two, says it’s a conversion lag instead. Either way, the usual purchase funnel’s stages haven’t changed. Awareness, consideration, and choice still happen. Now, more just happens inside a model’s synthesis of the market instead of inside the shopper’s own research.
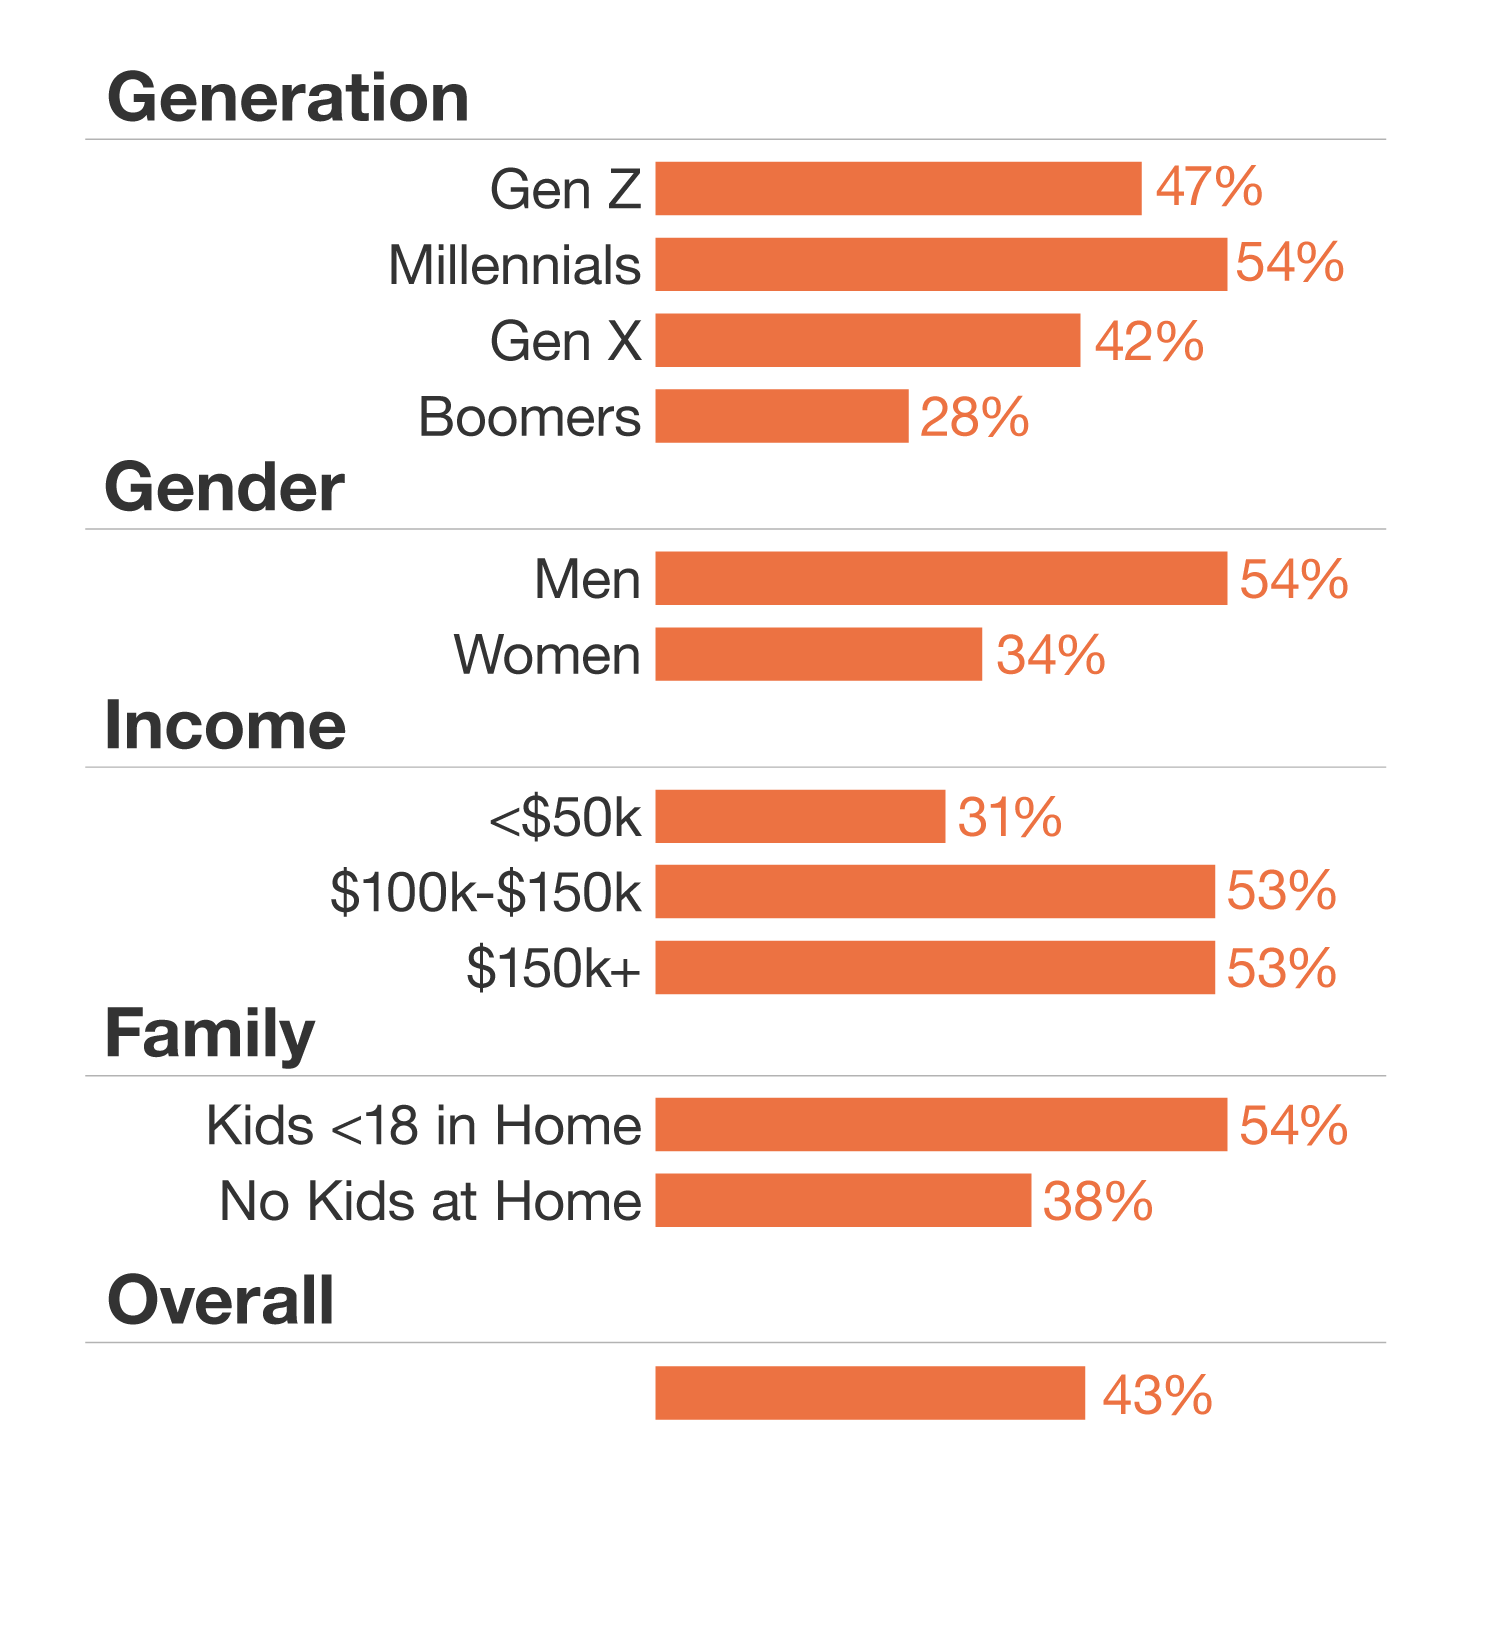
What the Model Does With Your Brand
It’s clear more consumers are using AI to help them shop, but what is going on under the hood? Basically, the AI system starts with some product information, then goes online and reads everything, and then finally reports a consensus. When I ask an AI what running shoes to buy, the model looks for reviews, forum threads, retailer listings, editorial roundups, and spec sheets. It then weighs this information against each other including what it already “knows” about your brand and the category and finally compresses it into a summary with a recommendation in it. A well written product page is one input among many. And a few great reviews can’t outweigh mixed sentiment across the web because the model is specifically built to average past outliers.
Many consumers are willing to accept this compression of information. Comfort with AI review summaries (66%) and AI product recommendations (65%) is now mainstream, and it declines as autonomy increases: 59% are comfortable with an in-app AI shopping assistant, 54% with a voice assistant reordering, 42% with an agent that reorders on its own.
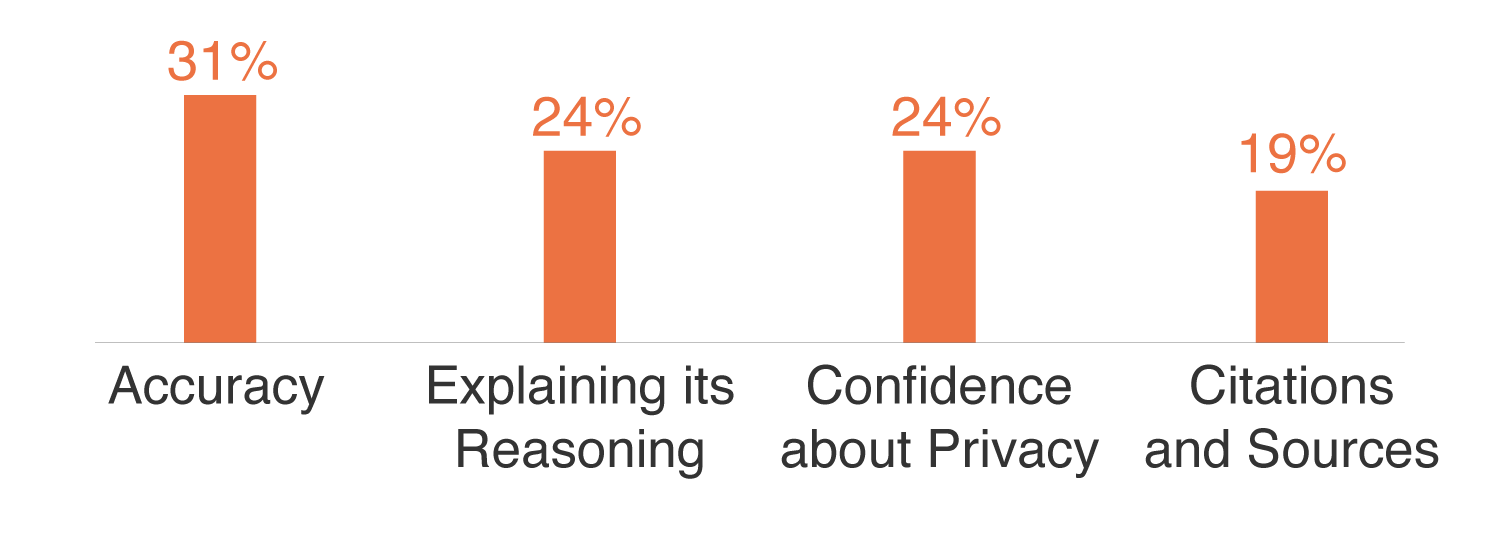
Trust appears to be one of the main drivers of AI shopping. The top builder of trust in AI shopping tools is accuracy (31%), followed by the tool explaining its reasoning (24%) and confidence about privacy (24%). Citations and source links matter to 19% overall. But among regular AI shoppers, citations matter 2.4 times the rate of non-users (32% versus 13%). As the market gains experience, verifiability matters more.
On the other side, the distrust can be a deal breaker. A third of shoppers (33%) say confident-but-wrong answers would break their trust, which is second only to data misuse (41%). And after a bad answer, shoppers will act: 32% will go back to a traditional search engine, 25% say they’d stop using the tool entirely, and only 15% would change nothing. When AI misstates your price, your specs, or your availability, the shopper doesn’t try to find out why. The sale just disappears.
Many people are now using an AI intermediary to read everything about your brand and are likely to leave if the system makes a mistake. In the second part of this analysis, we’ll look at where this heads next with agents that buy on their own, the 37% of consumers who are open to AI shopping but haven’t converted, and how to measure a journey that happens inside a model.
Greg Robison, PhD
Founding Partner & CTO of F’inn
Methodology: F’inn general population survey, n=501 US adults, fielded June 2026. Subgroup bases: Millennials n=155, parents with children under 18 at home n=172, household income $100K+ n=139, men n=249, women n=246, regular AI shoppers n=97.